How do you buy a home in Carmel Valley without confusing the search with the closing period?
You treat the purchase as two separate clocks. The first runs from preparation through the search until a seller accepts your offer, and its length depends on you and the inventory. The second begins at acceptance and covers inspections, appraisal, underwriting, and closing. Buyers who plan for Carmel Valley without confusing the two phases make better decisions on financing, lease end dates, and moving logistics.
Key Takeaways
- The time it takes to win a Carmel Valley home has no standard length, because it depends on your readiness, your criteria, and what comes to market.
- The contract-to-close period starts only when an offer is accepted, and its deadlines come from your executed purchase agreement and your lender's requirements.
- A preapproval letter is an early screening step, and final underwriting still verifies the specific property and updated financial documents after acceptance.
- A home inspection and a lender's appraisal are different steps, and a satisfactory appraisal never replaces an inspection.
- According to the California Department of Real Estate, the deed is generally recorded at the county recorder's office within one to three days after title is issued and escrow closes.
William Smith, Founding Broker of the Carmel Luxury Group at Coldwell Banker Realty, has guided buyers through Monterey County purchases since 1990. The most common planning mistake he sees is a buyer who hears a closing period quoted and assumes that is the length of the whole process. It isn't, and the gap between the two can affect your rental notice, your rate lock, and your moving date.
What happens before you win a Carmel Valley home?
Before acceptance, you are preparing, searching, and competing, and none of it has a countdown. This phase can take weeks or months depending on how ready you are and how closely available homes match what you want.
Preparation is a logistics project
Treat this phase as logistics, not as part of the closing countdown. The work that matters here includes:
- Lender preapproval, so you know your financing is real before you write an offer.
- Income and asset documentation gathered and ready to send.
- A credit review, so nothing surprises you mid-contract.
- Proof of funds for the required deposit and closing funds.
- Clear criteria for acceptable areas and property types.
- Readiness to schedule inspections quickly once you're under contract.
William's view is that preparation creates results on the buy side as well as the sell side. A buyer who has done this work can act decisively on the right property. A buyer who hasn't spends the first days of a good opportunity catching up.
Know which "Carmel" you're shopping in
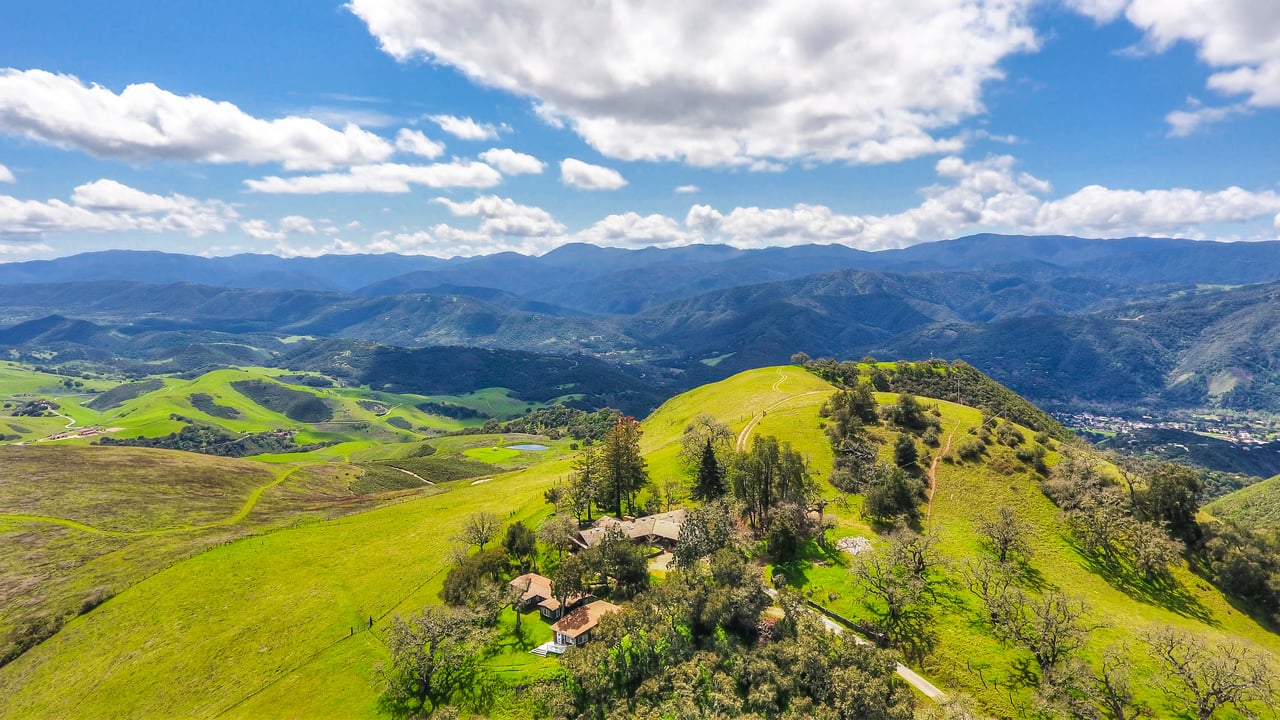
Carmel Valley is an unincorporated community in Monterey County. The City of Carmel-by-the-Sea is a separate municipality. Market reports label areas "Carmel," "Carmel Valley," by ZIP code, or as broader Monterey County geography, and those datasets are not interchangeable. If you want current conditions for the specific area you're targeting, that is a conversation to have with William directly. The Carmel Valley buying guide covers the area in more depth.
How quickly do you need to submit an offer?
When the right home appears, you should be ready to move quickly, because well-prepared competing buyers may also act. Preparation is what makes speed possible. Because Carmel Valley properties are often spread across rural and semi-rural areas, access arrangements and travel time can affect how fast you see a home in person. Describing current competitive conditions in numbers is a job for a live consultation, since they change from one property to the next.
What happens between acceptance and getting the keys?
Once the seller accepts, the contract-to-close clock starts, and its deadlines come from your executed purchase agreement and your lender's requirements. There is no universal California closing timetable, so read your own contract rather than relying on a general rule of thumb.
The steps that follow acceptance
After acceptance, the work commonly includes:
- Opening escrow and depositing funds with the title company.
- Inspections and investigations of the property.
- Review of the seller's disclosures.
- The lender's appraisal.
- Final underwriting and satisfaction of lender conditions.
- Title review and insurance coordination.
- Final loan documents, funding, and recording.
Inspection and appraisal are different jobs
An inspection evaluates the property's condition and potential defects, and it works for you. The appraisal works for the lender. Per the California Department of Real Estate, the lender's appraiser evaluates the property using comparable homes to determine value. A satisfactory appraisal tells you the lender is comfortable with the collateral. It tells you nothing about the roof, the septic system, or the drainage.
Preapproval does not end underwriting
Preapproval is an earlier screening step. After acceptance, underwriting generally requires verification of the specific property, updated financial information, and documentation that satisfies the lender's conditions. This is why you should keep your finances stable and respond to lender requests quickly through closing.
Escrow, lender, and recorder are separate milestones
Several parties move the transaction forward, and each controls a different piece:
Milestone | Who controls it | What it means for you |
|---|---|---|
Escrow and title | The title company or other escrow holder | Coordinates documents and funds |
Loan approval and funding | Your lender | Final underwriting and conditions must be satisfied |
Recording | The county recorder | The deed becomes part of the public record |
Contract deadlines | Your executed purchase agreement | Sets the dates for inspections, contingencies, and closing |
Recording is the public-record step after escrow closes, and the DRE notes it generally happens within one to three days. It is not the full home-search timeline, and your contract controls the details of possession, so confirm those terms rather than assuming.
How do you buy in Carmel Valley without confusing the two clocks?
You build a plan for each clock separately and take every contract date from your own agreement. The search clock is flexible and the contract clock is not, so protect the second one with preparation done during the first.
Plan around the contract, not a generic number
No authoritative, current Carmel-specific closing-time figure should stand in for your contract's actual closing date. Anyone quoting you a "typical" number without seeing your contract is guessing. Use the dates in your executed agreement, and ask your lender and title company for their current turnaround on each step.
Build in room for the parts you don't control
Inspector availability, property access, lender conditions, and appraisal scheduling can all shift a date. A delayed appraisal or loan approval can push back closing, so avoid locking rigid commitments, such as a lease ending the day before your scheduled close, until you're confident in the schedule. Properties with more complexity, such as acreage, wells, septic, or older construction, often take more coordination, so build that into your logistics.
Money questions belong in a personalized conversation
What you'll pay at closing depends on your loan, your contract, and the property, and the allocation of closing costs is a matter of contract, not a universal local rule. Your title company and lender can give you itemized figures, and William can walk you through what to expect before you write an offer. Your exact timeline depends on your financing, the property, and your move-out date, which is where a conversation with someone who knows this market saves you from guessing.
Buying in Carmel Valley without confusing the search with the closing period starts with knowing that preparation, competition, and contract work are separate jobs on separate clocks. If you'd like to map yours out before you start looking, schedule a consultation with William, and he'll walk you through each phase for your situation.
You can read what clients say about working with William on Google, Zillow, and Realtor.com.
FAQ
How long does it usually take to buy a house in Carmel Valley from preapproval to closing?
There is no single answer, because the total is the search phase plus the contract phase. The search phase depends on your readiness and what's available, and the contract phase follows the dates in your accepted agreement. Ask your lender and title company for current turnaround times rather than relying on a generic figure.
Is the time to close separate from the time it takes to find and win a home?
Yes, they are two distinct phases. The closing period only begins once a seller accepts your offer. Weeks or months of preparation, searching, and competing can come before that, so a quoted closing period is never the full timeline.
What should I do before making an offer on a Carmel Valley house?
Get preapproved, gather your income and asset documents, review your credit, and confirm your proof of funds for the deposit and closing. Define the areas and property types you'll consider, and be ready to schedule inspections quickly. Doing this ahead of time lets you act decisively when the right property appears.
Can a delayed appraisal or loan approval push back the closing date?
Yes, either one can. The appraisal supports the lender's valuation, and final underwriting must be satisfied before funding. Your contract sets the deadlines, so talk with William and your lender early if a step is running behind, and review your options under the agreement.
When does the deed record, and when do I actually get the keys?
The deed is generally recorded at the county recorder's office within one to three days after title is issued and escrow closes, according to the California Department of Real Estate. Possession terms are set in your contract, so confirm when you take possession rather than assuming it matches the recording moment.
Equal Housing Opportunity. William Smith, Founding Broker, Carmel Luxury Group at Coldwell Banker Realty, CA-DRE #01064866. Affiliated real estate agents are independent contractor sales associates, not employees. This article is general information, not legal, tax, or financial advice; confirm your own numbers and deadlines with your title company, tax advisor, or lender.